Key Takeaways
- Renovation Loans
- Financing
- FHA 203(k)
- Written by Mark Nesci, Broker Associate with Baird & Warner
By Mark Nesci, Mark Nesci Real Estate Services
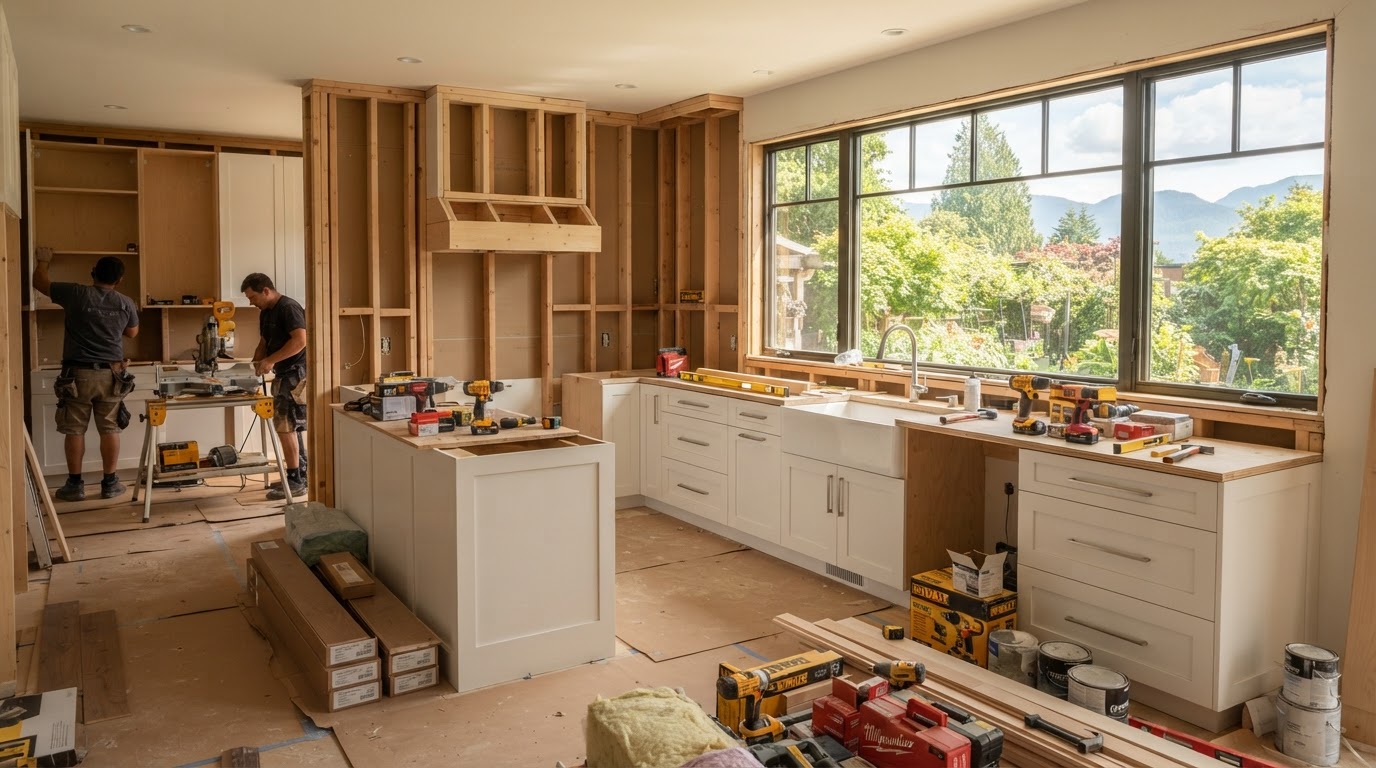
On the North Shore, buyers often find the perfect street, the right school district, and a great lot, attached to a house that needs work. Dated kitchens, original baths, and older systems are common in established neighborhoods. The usual plan is to buy now and renovate later with savings. But there's another option many buyers don't know about: a renovation loan that covers both.
Quick Answer
A renovation loan lets you finance a home's purchase price and the cost of planned improvements in one mortgage. The two most common options are Fannie Mae's HomeStyle Renovation loan, a conventional loan, and the FHA 203(k) loan, which is government-insured. Both base the loan on the home's value after the work is done, and both have rules on budgets, contractors, and timelines.
What is a renovation loan?
It's a single mortgage that includes both the purchase price of a home and the money for renovations.
Instead of buying a home and then finding separate financing for updates, the renovation budget is built into your loan from the start. The renovation funds are typically held in an account and paid out to your contractor as the work is completed and inspected.
The loan amount is based on the home's expected "as-completed" value, meaning what an appraiser estimates the home will be worth after the renovations.
What is a Fannie Mae HomeStyle Renovation loan?
It's a conventional mortgage that lets you finance improvements, renovations, or repairs at the time of purchase or as a refinance.
According to Fannie Mae, renovation funds can be up to 75% of the lesser of the purchase price plus renovation costs, or the home's as-completed appraised value. There's no set list of approved projects, so it can cover a wide range of work, from a new kitchen to a major remodel.
Because it's conventional, it can also be used for second homes and investment properties, subject to Fannie Mae's guidelines.
What is an FHA 203(k) loan?
It's a renovation mortgage insured by the Federal Housing Administration, and it comes in two versions.
The Limited 203(k) covers smaller, non-structural projects, with a maximum renovation amount of $75,000. The Standard 203(k) covers larger projects, including structural work, with a $5,000 minimum and no set maximum, though FHA loan limits still apply. The Standard version requires a HUD-approved consultant.
FHA 203(k) loans are for primary residences. On the North Shore, many home prices exceed FHA loan limits, so a conventional or jumbo renovation option may be the better fit for higher-priced homes.
Is a renovation loan right for you?
It can be a smart fit if the home's location and lot are right, but the house needs updates you'd rather finance than pay for out of pocket.
A few things to know before you decide:
- Get solid contractor bids early. The lender needs a detailed scope of work and budget before closing.
- Plan for a timeline. Renovation loans come with deadlines to complete the work.
- Expect more paperwork. Inspections and draw requests add steps compared to a standard mortgage.
- Think about value. The renovations should make sense for the home and the neighborhood, so you're not over-improving.
Why does having one team help?
Renovation loans have more moving parts than a typical purchase: the home search, the renovation plan, contractor bids, the appraisal, and the financing all have to line up.
When your real estate guidance, contracting knowledge, and mortgage expertise work together, it's easier to judge a home's potential, build a realistic budget, and keep the project on track from offer to final walkthrough.
The Bottom Line
A renovation loan can turn a North Shore house with good bones into the home you actually want, with one mortgage covering both the purchase and the updates. Fannie Mae's HomeStyle Renovation and the FHA 203(k) each have their own rules, budgets, and timelines. Start with a clear renovation plan and solid bids, and you can buy in the right location without waiting years to make the home your own.
Frequently Asked Questions
Can I include renovation costs in my mortgage?
Yes. Renovation loans like Fannie Mae's HomeStyle Renovation and the FHA 203(k) let you finance both the purchase and the renovation in one mortgage.
How much can I borrow for renovations with a HomeStyle loan?
According to Fannie Mae, renovation funds can be up to 75% of the lesser of the purchase price plus renovation costs, or the as-completed appraised value.
What is the limit on an FHA Limited 203(k) loan?
The Limited 203(k) has a maximum renovation amount of $75,000 for non-structural projects. Larger or structural projects use the Standard 203(k).
Can I use an FHA 203(k) loan on a second home?
No. FHA 203(k) loans are for primary residences. Fannie Mae's HomeStyle Renovation loan can be used for second homes and investment properties, subject to its guidelines.
Keep Learning
- Read: Top 5 Renovation Projects with the Highest ROI
- Read: The Triple Advantage: Why Working with a Realtor, Contractor, and Mortgage Lender in One Changes Everything
- Read: Buying a North Shore Teardown? Check These Rules First
Found a North Shore home with potential? Let's look at the numbers, the renovation plan, and the financing together. Schedule a consultation.
Mark Nesci
Realtor, Mortgage Banker & General Contractor - MAN Real Estate Services
Mark Nesci brings over 30 years of North Shore experience across real estate, mortgage banking, and general contracting. He helps buyers evaluate construction issues and financing, and helps sellers price and prepare homes for maximum return.
Learn more about MarkReady to Discuss Your Real Estate Goals?
Whether you're buying, selling, or just exploring your options, get expert guidance tailored to Chicago's North Shore market.
Schedule a Consultation